- Tags: Office Market News,
- Author: Admin STS,
- Date posted: 17/10/2026
Vietnam Office Market Q3 2026: Rents, Vacancy, Q4 Outlook
Office Market Report: Ho Chi Minh City, Hanoi and Da Nang – Q3 2026
In Q3 2026, Ho Chi Minh City held rents and occupancy near 90% but recorded negative net absorption; Hanoi faced pressure from new Grade A supply; Da Nang stayed small but is driven by foreign direct investment (FDI). This report covers rents, occupancy and supply in all three markets, a Q4 2026 outlook, and tips for companies looking for office space for lease.
Market Overview
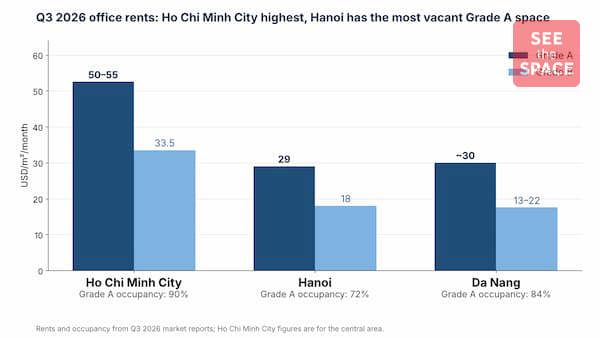
Ho Chi Minh City has the highest rents and the strongest occupancy. Hanoi ranks second on rent but has the most vacant Grade A space. Da Nang's Grade A rent is similar to Hanoi's, with higher occupancy. Figures below come from Q3 2026 market reports.
| Indicator (Q3 2026) | Ho Chi Minh City | Hanoi | Da Nang |
|---|---|---|---|
| Grade A rent (USD/m²/month) | 50–55 (central area) | 29 | about 30 |
| Grade B rent (USD/m²/month) | 33.5 | 18 | 13–22 |
| Grade A occupancy | 90% | 72% | 84% |
| Grade B occupancy | 91% | 84% | 89% |
| Total supply | nearly 3 million m² | 2.4 million m², 193 projects | 204,000 m² |
| Main trend | Stable rents, negative net absorption | Intense Grade A competition | 26,000 m² of new supply |
Ho Chi Minh City Office Market
Rents and occupancy are stable, but tenant expansion has stalled. Q3 2026 saw negative net absorption in every grade, after five consecutive positive quarters, mainly because some tenants downsized.
- Supply of nearly 3 million m², occupancy near 90%, average rent of VND 870,000/m²/month.
- Landlords are prioritizing tenant retention over rent changes.
- Leasing is concentrated in finance, insurance and real estate; information technology; and retail and distribution.
- New supply: more than 175,000 m² is forecast for 2026–2028, with about 76% of new Grade A space in the International Financial Centre area.
Latest figures by grade (Q2 2026):
| Grade | Rent (USD/m²/month) | Vacancy |
|---|---|---|
| Grade A | 47.2 | about 17% |
| Grade B | 27.1 | about 13% |
Looking at the core area? See Cho thuê Văn phòng Quận 1 | TP.HCM and Office for Lease in District 3 HCMC
Hanoi Office Market
Supply pressure is concentrated in Grade A. Grade A occupancy is only 72%, the lowest of the three cities, while overall market occupancy fell to 83% as new Grade A projects opened.
- Total supply of 2.4 million m² across Office for lease in Hà Nội 193 projects; average rent up 2% year on year.
- Demand is mainly relocation, upgrades to better space and cost optimization.
- Grade A performance varies by location: in Q2 2026, central Grade A occupancy was 95% versus 81% outside the center.
- New supply: IFC Hanoi and Oriental Square added more than 73,000 m² of net leasable area in Q2. The western districts are expected to add about 400,000 m² in 2026–2028, roughly 83% of the market's new supply.
- Market-wide net absorption in Q2 stayed positive, at about 3,200 m².
| Grade | Rent (USD/m²/month) | Occupancy |
|---|---|---|
| Grade A | 29 | 72% |
| Grade B | 14.8–18 | 84% |
See more Office for lease in Hà Nội by district.
Da Nang Office Market
A small market that is growing fast: more than 26,000 m² of new supply arrived in Q3 2026, lifting total space to 204,000 m², of which Grade A is nearly 20,000 m² and Grade B more than 180,000 m².
| Indicator | Grade A | Grade B |
|---|---|---|
| Rent (USD/m²/month) | about 30 | 13–22 |
| Occupancy | 84% | 89% |
- Demand is led by FDI, which accounts for 82% of leased area. The most active sectors are information technology; finance, insurance, real estate, manufacturing and consulting; and education, with FPT and Viettel among the major names.
- Room to grow comes from the 300-hectare International Financial Centre and the planned free trade zone. Projects of about 100,000 m² are expected to open from Q4 2027.
- Deals of 1,000–2,000 m² from international tenants are starting to appear, and more than 100,000 m² of new supply is forecast by 2028.
Considering a branch office? Browse Office for Rent in Da Nang – Grade A B C Updated 2026
Q4 2026 Outlook
Grade A rents are likely to move sideways in all three cities; the difference lies in occupancy. No dedicated Q4 forecast figures have been published, so the table below is our estimate, derived from Q2–Q3 trends and the announced supply schedule.
| City | Grade A rent | Occupancy | Rationale |
|---|---|---|---|
| Ho Chi Minh City | Flat (±2%) | 89–91%, weak to neutral absorption | Next phase expected to be cautious and selective; landlords prioritize retention, no upward rent pressure |
| Hanoi | 0 to −2% | 70–75%, slow recovery | Nearly 495,000 m² from 18 projects by 2028, mostly Grade A in the west; landlords keep offering incentives to fill space |
| Da Nang | Stable around USD 30 | About 80–85% | Beyond the 26,000 m² just delivered, no large supply before Q4 2027; FDI demand is supportive |
Three signals to watch when Q4 reports come out:
- Whether Ho Chi Minh City's net absorption turns positive again.
- How fast IFC Hanoi and Oriental Square fill up.
- The first large leases at the International Financial Centres in Ho Chi Minh City and Da Nang.
If FDI inflows stay strong, Grade A demand could pick up sooner than estimated, especially in Ho Chi Minh City.
What Tenants Should Do in Q4
The market favors tenants in Hanoi and is fairly balanced in Ho Chi Minh City, so now is a good time to negotiate. This is our view based on the figures above, not investment advice.
- Hanoi: with high Grade A vacancy, negotiate rent-free periods, fit-out support and flexible terms. See our tips for negotiating office rent.
- Ho Chi Minh City: landlords are holding rents but want to keep tenants, so early renewals tend to go smoothly. To save cost, consider offices outside the central area, which are significantly cheaper.
- Da Nang: no large new supply is due before late 2027, so companies needing Grade A space soon should commit early.
- Need flexibility: if headcount is uncertain, look at serviced offices and coworking instead of a long lease.
Frequently Asked Questions
Where is Grade A office rent highest? Ho Chi Minh City, at about USD 50–55/m²/month in the central area, nearly double Hanoi (about USD 29) and Da Nang (about USD 30).
Which city has the lowest Grade A occupancy? Hanoi, at about 72% in Q3 2026, because many new projects opened in the western and inner-city districts.
Will office rents rise or fall in Q4 2026? We estimate Grade A rents will stay flat in all three cities, with Hanoi possibly easing by up to 2%.
Is Da Nang a good place to rent an office? Grade B rent is only USD 13–22/m²/month with 89% occupancy, which suits technology, service and FDI companies opening a branch.
Need Help Finding an Office?
📞 Phone: 0768 999 647
📩 Email: leasing@seethespace.vn
🌐 Website: seethespace.vn
SEE the SPACE - Your Space, Expertly Guided
SEE the SPACE is a professional real estate leasing consultancy dedicated to helping clients discover and secure the office and commercial spaces that best fit your needs
Tell us your required area, budget and preferred location, and we will suggest suitable buildings. Contact Us